Fitch SOCAR-ın reytinqini təsdiqlədi, kredit profilini yüksəltdi
Fitch: SOCAR-ın neft hasilatı azalır, amma maliyyə göstəriciləri güclənir. Fitch SOCAR-ın İtaliya alışını müsbət qiymətləndirdi – Türkiyədə 7 milyard dollarlıq plan gündəmdə.
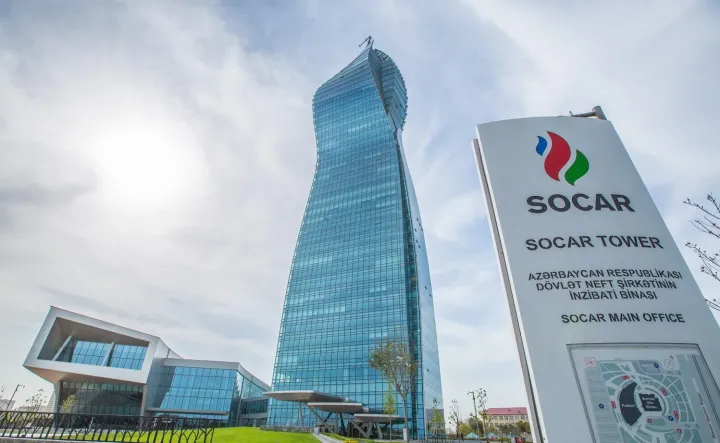
Beynəlxalq kredit reytinqi agentliyi “Fitch Ratings” Azərbaycan Dövlət Neft Şirkətinin (SOCAR) uzunmüddətli emitent defolt reytinqini (IDR) və təminatsız prioritet borc reytinqini “BBB-” səviyyəsində təsdiqləyib. Reytinq üzrə proqnoz “Stabil” saxlanılıb.
Marja xəbər verir ki, bu barədə “Fitch Ratings” məlumat yayıb.
Agentlik eyni zamanda SOCAR-ın müstəqil kredit profilini (SCP) “bb-”dən “bb” səviyyəsinə yüksəldib. Fitch bunu şirkətin borclanma göstəricilərinin yaxşılaşması ilə əlaqələndirib. SOCAR-ın kredit profilinin orta miqyaslı neft-qaz hasilatı, inteqrasiya olunmuş biznes modeli və güclü maliyyə göstəriciləri ilə dəstəkləndiyi bildirilib.
Fitch qeyd edib ki, SOCAR tam şəkildə Azərbaycan dövlətinə məxsusdur və şirkətin reytinqi Azərbaycanın “BBB-/Stabil” suveren reytinqinə bərabərləşdirilib. Buna dövlətin SOCAR-a maliyyə zəmanətləri, pul və kapital qoyuluşları formasında dəstəyi, eləcə də şirkətin ölkənin neft-qaz layihələrinin həyata keçirilməsində strateji rolu əsas verir.
Agentliyin məlumatına görə, 2025-ci ilin sonunda dövlət zəmanətləri SOCAR-ın borcunun 25%-ni əhatə edib. “Cənub Qaz Dəhlizi”nin avrobondlarının ödənilməsindən sonra bu göstəricinin təxminən 12%-ə endiyi qiymətləndirilir. Fitch hesab edir ki, zərurət yarandığı halda Azərbaycan hökuməti SOCAR-a birbaşa dəstək göstərəcək.
SOCAR-ın hasilatında azalma
Fitch bildirib ki, SOCAR-ın özünün idarə etdiyi yataqlarda neft hasilatı 2025-ci ildə 5% azalıb və geriləmə 2026-cı ilin ilk yarısında da davam edib. Qaz hasilatı 2025-ci ildə 1% artsa da, 2026-cı ildə azalma qeydə alınıb.
“Azəri-Çıraq-Günəşli” yataqlar blokunda ümumi hasilat 2025-ci ildə təxminən 4%, 2026-cı ildə isə təxminən 2% aşağı düşüb. “Şahdəniz” üzrə ümumi hasilat 2025-ci ildə 4% azalıb. Bunun fonunda SOCAR-ın idarə etdiyi yataqlarda qazma işlərinin həcmi 2026-cı ilin ikinci rübündə üçdə bir artırılıb.
Fitch həmçinin “Şahdəniz” layihəsinin yeni inkişaf mərhələsində 3 milyard dollarlıq layihənin 2029-cu ildən etibarən əlavə 50 milyard kubmetr qaz və 25 milyon barel maye karbohidrogen hasil etməsinin gözlənildiyini bildirib.
“Abşeron” yatağının ikinci mərhələsi üzrə isə TotalEnergies, SOCAR və ADNOC-un 2026-cı ildə yekun investisiya qərarı qəbul edəcəyi gözlənilir. Layihə nəticəsində hasilatın hazırkı gündəlik təxminən 30-40 min barel neft ekvivalentindən 140 min barel neft ekvivalentinə yüksəlməsi nəzərdə tutulur.
Fitch SOCAR-ın İtaliyadakı alışını müsbət qiymətləndirir
Agentlik SOCAR-ın “Italiana Petroli S.p.A.” şirkətinin alınmasını tamamladığını və əməliyyatın şirkətin öz vəsaiti hesabına maliyyələşdirildiyini bildirib.
Fitch bu alışı SOCAR üçün müsbət qiymətləndirib və qeyd edib ki, əməliyyat şirkətin beynəlxalq fəaliyyətini şaxələndirir və downstream biznesində mövqelərini genişləndirir.
“Italiana Petroli”nin aktivlərinə Ankona və Novarada ümumi illik 10 milyon ton emal gücünə malik iki neft emalı zavodu, İtaliyada təxminən 4,5 min yanacaqdoldurma məntəqəsi, həmçinin saxlama və logistika aktivləri daxildir.
Türkiyəyə 7 milyard dollarlıq investisiya planı
Fitch SOCAR-ın Türkiyədə 7 milyard dollarlıq genişlənmə planını da diqqətə çatdırıb.
Plan Türkiyənin poliolefin idxalından asılılığını azaltmaq və rəqabət qabiliyyətini yüksəltmək məqsədilə yeni istehsal müəssisələrinin yaradılmasını nəzərdə tutur. SOCAR rəhbərliyinin layihə üzrə yekun investisiya qərarını 2026-cı ilin sonuna qədər verməyi planlaşdırdığı qeyd edilib.
SOCAR-ın EBITDA-sı 12 milyard manata çata bilər
Fitch-in məlumatına görə, SOCAR-ın nəzarət olunmayan paylara dividendlər çıxıldıqdan sonra EBITDA göstəricisi 2025-ci ildə 9,3 milyard manata yüksəlib. 2024-cü ildə bu göstərici 5 milyard manat olub.
Agentlik 2026-cı ildə EBITDA-nın 12 milyard manata çatacağını, 2028-2029-cu illərdə isə 7,5-8 milyard manat intervalına enəcəyini proqnozlaşdırır.
SOCAR-ın xalis borc/EBITDA göstəricisi 2025-ci ildə 1,0x təşkil edib. Fitch 2026-cı ildə də bu göstəricinin təxminən 1,0x səviyyəsində qalacağını, 2029-cu ilə doğru isə təxminən 2,0x-a yüksələcəyini gözləyir.
Fitch-in baza ssenarisində SOCAR-ın 2026-2030-cu illərdə kapital xərclərinin illik orta hesabla təxminən 4 milyard manat, dövlətə dividend və digər ödənişlərinin isə orta hesabla 1,8 milyard manat olacağı nəzərdə tutulur.
XXX
Fitch Affirms SOCAR at 'BBB-'; Outlook Stable
Fitch Ratings - London - 14 Sep 2026: Fitch Ratings has affirmed State Oil Company of the Azerbaijan Republic's (SOCAR) Long-Term Issuer Default Rating (IDR) and senior unsecured rating at 'BBB-'. The Outlook on the Long-Term IDR is Stable.
SOCAR is fully owned by the state and its rating is equalised with that of Azerbaijan (BBB-/Stable) under our Government-Related Entities (GRE) Rating Criteria. The rating equalisation is underpinned by state support provided to the company through financial guarantees, cash contributions and equity injections, plus SOCAR's social functions and its importance as a state vehicle for the development of oil and gas projects.
We have revised SOCAR's Standalone Credit Profile (SCP) up to 'bb' from 'bb-' due to improved leverage metrics. SOCAR's SCP reflects its mid-scale oil and gas production, integrated business model, strong financial profile and corporate governance limitations.
Key Rating Drivers
Rating Equalisation: Fitch's assessment of SOCAR under its GRE Rating Criteria results in a GRE score of 40 out of a maximum 60, which means support is extremely likely. Combined with SOCAR's SCP of 'bb', this leads to the equalisation of SOCAR's rating with Azerbaijan's sovereign rating.
Strong Decision-Making and Oversight: The Azerbaijani government has significant control over SOCAR's operations, financial performance and strategic decisions, demonstrating robust oversight. The company's top management is appointed by the President of Azerbaijan. The state has also significant influence over SOCAR's strategy and operations.
Strong Precedents of Support: The government has a history of considerable support, including capital injections and debt guarantees. According to SOCAR, state guarantees covered 25% of its debt at end-2025, following the consolidation of Southern Gas Corridor (SGC). The ratio has historically been much lower (4% at end-2023) and we estimate to have decreased to around 12% following repayment of SGC's eurobonds. SOCAR's standalone profile remains solid, supported by favourable hydrocarbons prices, reducing the immediate need for support. Nonetheless, we believe the government would provide direct support if required.
Strong Preservation of Government Policy Role: SOCAR has an important role in Azerbaijan's economy as an oil and gas producer and seller of refined products on the domestic market and its involvement in major energy projects, such as the SGC, which are vital for the country's strategic interests and its energy security. SOCAR also holds stakes in and represents the government in various oil and gas joint ventures vital to the country's hydrocarbon output. SOCAR is the largest employer, taxpayer, and the state's vehicle for the development of oil and gas industry in the country.
Very Strong Contagion Risk: We assess contagion risk as strong. This reflects the potential negative impact on the Azerbaijani government's access to capital markets should SOCAR default. We view SOCAR as a reference issuer for the financing market relevant to its government.
Production Declines: SOCAR's own-operated oil production fell 5% in 2025, and the decline continued in 1H26. Gas production rose 1% in 2025 but has declined in 2026. Production from production-sharing agreements also fell. Azeri-Chirag-Deepwater Gunashli (ACG) gross production declined about 4% in 2025 and about 2% in 2026, while Shah Deniz (SD) gross production fell 4% in 2025.
Development Initiatives Pick Up: In response to the decline, drilling at SOCAR-operated fields increased by one-third in 2Q26. Other measures include improved recovery and development of previously untapped non-associated gas in the ACG production sharing agreement (PSA). A new development stage at the SD PSA involving a USD3 billion project that is expected to add 50 bcm of gas and 25 million barrels of liquids from 2029. Separately, Total, SOCAR and ADNOC, expect to make the final investment decision in 2026 on stage 2 development of the Absheron field. This would raise production to 140 kboe/d from about 30 kboe/d-40 kboe/d.
Italian Acquisition Diversifies Operations: SOCAR completed the acquisition of italiana petroli S.p.A. (IP). SOCAR funded the acquisition with cash. IP generated EUR616 million of adjusted EBITDA and EUR395 million of reported EBITDAR. We view the acquisition positively for SOCAR as it diversifies and adds downstream integration to its international footprint. IP's assets include two operated refineries in Ancona and Novara with total refining capacity of 10 million tonnes, 4.5 thousand retail stations in Italy selling about 8.5 million tonnes of fuel, and wholesale fuel sales of 7.3 million tonnes supported by storage and logistics assets.
Ambitious Growth Plans in Turkiye: SOCAR outlined an ambitious USD7 billion expansion plan in early 2025 to build new facilities aimed at reducing Turkiye's polyolefin import dependence and boosting competitiveness. We understand from management that it intends to make the final investment decision by end-2026. We have not incorporated potential project capex or its impact into our forecasts, pending the project's final key details.
Comfortable Leverage: SOCAR'S 2025 EBITDA after dividends to non-controlling interests was AZN9.3 billion, up from AZN5 billion in 2024, reflecting the full-year impact from the consolidation of SGC and the STAR refinery. As a result, EBITDA net leverage was low at 1.0x. We expect leverage to remain stable at about 1.0x in 2026 as increased capex and M&A spending is offset by high oil and gas prices and refining margins. We forecast EBITDA after dividends to non-controlling interests at AZN12 billion in 2026 before declining to AZN8-7.5 billion by 2028-2029. This leads to EBITDA net leverage normalising to about 2x by 2029.
Peer Analysis
SOCAR's SCP is similar to that of JSC National Company KazMunayGas (BBB/Stable; SCP: bb). SOCAR's scale is somewhat larger than KazMunayGas's but the latter maintains lower leverage. SOCAR's business profile is also constrained by weaker financial transparency.
JSC Uzbekneftegaz's (BB/Stable) 'b' SCP reflects its weaker profitability relative to SOCAR and higher leverage. JSC National Company QazaqGaz's (BB+/Stable) 'b' SCP reflects the weak profitability of its consolidated operations. However, its cash flow generation is supported by large dividends from joint ventures.
SOCAR's SCP is two notches below OQ S.A.O.C.'s (BBB-/Stable) 'bbb-' SCP reflecting OQ's lower leverage, somewhat smaller scale and better financial transparency.
The ratings of KazMunayGas, SOCAR, OQ and Uzbekneftegaz are equalised with their respective sovereign ratings (Kazakhstan, Azerbaijan, Oman and Uzbekistan); QG is rated two notches below the Kazakhstani sovereign.
Fitch’s Key Rating-Case Assumptions
- Brent crude price: USD87 perbarrel (bbl) in 2025; USD65/bbl in 2026; USD60/bbl thereafter
- Title transfer facility (TTF) natural gas prices at USD14/mcf in 2026, USD9/mcf in 2027, USD7/mcf in 2028-2029 and USD5/mcf thereafter
- Production decline stabilising from 2028
- USD/AZN exchange rate: 1.7
- Capex averaging about AZN4.0 billion annually over 2026-2030
- AZN250 million annually to support Petkim until 2027
- Dividends and distributions to the government averaging AZN1.8 bn annually over 2026-2030
Corporate Rating Tool Inputs and Scores
Fitch scored the issuer as follows, using our Corporate Rating Tool (CRT) to produce the Standalone Credit Profile (SCP):
Business and financial profile factors (assessment, relative importance): management ('bb', Moderate), sector characteristics ('bb+', Moderate), market and competitive positioning ('bbb-', Lower), diversification and asset quality ('bb+', Moderate), company operational characteristics ('bb+', Moderate), profitability ('bbb', Lower), financial structure ('bb+', Moderate), and financial flexibility ('bb-', Higher).
The quantitative financial subfactors are based on custom CRT financial period parameters: 10% weight for the historical year 2025, 10% for the forecast year 2026, 30% for the forecast year 2027, 30% for the forecast year 2028 and 20% for the forecast year 2029.
The governance assessment of 'good' has no impact.
The operating environment assessment of 'bb-' has no impact.
The SCP is 'bb'.
To derive the Long-Term IDR:
Application of Fitch's Government-Related Entities Rating Criteria results in a(n) equalized approach.
RATING SENSITIVITIES
Factors that Could, Individually or Collectively, Lead to Negative Rating Action/Downgrade
- A downgrade of Azerbaijan
- EBITDA net leverage or EBITDA gross leverage exceeding 3.0x or 3.5x on a sustained basis, which would lead to a downward revision of SOCAR's SCP but not necessarily a downgrade of the IDR
- Weakening state support
Factors that Could, Individually or Collectively, Lead to Positive Rating Action/Upgrade
- Upgrade of Azerbaijan's rating
- Improved financial transparency and EBITDA net leverage or EBITDA gross leverage below 2.0x or 2.5x on a sustained basis, which would lead to an upward revision of the SCP but not necessarily an upgrade of the IDR.
For Azerbaijan's rating sensitivities see: Fitch Affirms Azerbaijan at 'BBB-'; Outlook Stable, dated 5 June 2026
Liquidity and Debt Structure
At end-2025, SOCAR had AZN14 billion of cash and cash equivalents and about AZN1.5 billion of Fitch-adjusted marketable securities adequately covering AZN15.1 billion of short-term debt. During 2026, SOCAR addressed some of these maturities having repaid or refinanced AZN14.2 billion of debt with a mix of short-term and long-term debt.
Issuer Profile
SOCAR is the wholly state-owned national oil company of Azerbaijan.
REFERENCES FOR SUBSTANTIALLY MATERIAL SOURCE CITED AS KEY DRIVER OF RATING
The principal sources of information used in the analysis are described in the Applicable Criteria.
Public Ratings with Credit Linkage to other ratings
SOCAR's rating is equalised with the sovereign's.
MACROECONOMIC ASSUMPTIONS AND SECTOR FORECASTS
Click here to access Fitch's latest quarterly Global Corporates Sector Forecasts Monitor data file which aggregates key data points used in our credit analysis. Fitch's macroeconomic forecasts, commodity price assumptions, default rate forecasts, sector key performance indicators and sector-level forecasts are among the data items included.
Climate Vulnerability Signals
The results of our Climate.VS screener did not indicate an elevated risk for SOCAR.
ESG Considerations
SOCAR has an ESG Relevance Score of '4' for Governance Structure due to concentrated ownership and limited board independence, which has a negative impact on the credit profile, and is relevant to the rating[s] in conjunction with other factors.
SOCAR has an ESG Relevance Score of '4' for Financial Transparency due to weak information disclosure, which has a negative impact on the credit profile, which has a negative impact on the credit profile, and is relevant to the rating[s] in conjunction with other factors.
Müştərilərin xəbərləri
SON XƏBƏRLƏR
- 2 ay sonra
-
8 d. əvvəl
Azərbaycana daxil olan xarici valyuta çıxan valyutanı 1,4 milyard dollar üstələyib
-
38 d. əvvəl
Bil Qeytsdən süni intellekt və səhiyyə ilə bağlı xəbərdarlıqlar
-
-
1 saat əvvəl
Azərbaycan nefti orta hesabla 94,5 dollardan, qazı 313 dollardan ixrac edilib
- 1 saat əvvəl
-
1 saat əvvəl
Azərbaycana daxil olan pul baratları üzrə müsbət saldo 530 milyon dolları ötüb
-
1 saat əvvəl
Azərbaycanın cari əməliyyatlar balansının profisiti 2 dəfə artıb
- 1 saat əvvəl
-
1 saat əvvəl
Azərbaycan İnvestisiya Holdinqi və L’İMAD Strateji Əməkdaşlıq Sazişi imzalayıblar
-
1 saat əvvəl
Azərbaycan banklarına “Moody’s”dən müsbət qiymət: Sistem riskləri azalıb
- 2 saat əvvəl
-
2 saat əvvəl
Fitch SOCAR-ın reytinqini təsdiqlədi, kredit profilini yüksəltdi
Son Xəbərlər
İş elanlarına bax - azvak.az
Bil Qeytsdən süni intellekt və səhiyyə ilə bağlı xəbərdarlıqlar
Azərbaycandan ilk 6 ayda 3 milyard dollar kapital çıxarılıb
Fitch SOCAR-ın İtaliyadakı alışını müsbət qiymətləndirdi
SOCAR bu ölkədə 7 milyard dollar yatırmağa hazırlaşır
Ən çox oxunanlar

Fitch SOCAR-ın reytinqini təsdiqlədi, kredit profilini yüksəltdi
Bakcell-dən Wi-Fi modemi alın, ilk abunəliyiniz pulsuz olsun ®

Azərbaycan neftinin qiyməti 127 dolları keçib
Kağız əsaslı nəqliyyat sənədlərinin elektron formata keçirilməsi - Azərbaycanlı mütəxəssis Orxan Namazovun təqdimatı diqqət çəkib

Rəsmi məzənnələr açıqlandı
Ərəb şirkəti Naxçıvanda mineral ehtiyatların axtarışına qoşulur
SON XƏBƏRLƏR
- 2 ay sonra
-
8 d. əvvəl
Azərbaycana daxil olan xarici valyuta çıxan valyutanı 1,4 milyard dollar üstələyib
-
38 d. əvvəl
Bil Qeytsdən süni intellekt və səhiyyə ilə bağlı xəbərdarlıqlar
-
-
1 saat əvvəl
Azərbaycan nefti orta hesabla 94,5 dollardan, qazı 313 dollardan ixrac edilib
- 1 saat əvvəl
-
1 saat əvvəl
Azərbaycana daxil olan pul baratları üzrə müsbət saldo 530 milyon dolları ötüb
-
1 saat əvvəl
Azərbaycanın cari əməliyyatlar balansının profisiti 2 dəfə artıb
- 1 saat əvvəl
-
1 saat əvvəl
Azərbaycan İnvestisiya Holdinqi və L’İMAD Strateji Əməkdaşlıq Sazişi imzalayıblar
-
1 saat əvvəl
Azərbaycan banklarına “Moody’s”dən müsbət qiymət: Sistem riskləri azalıb
- 2 saat əvvəl
-
2 saat əvvəl
Fitch SOCAR-ın reytinqini təsdiqlədi, kredit profilini yüksəltdi